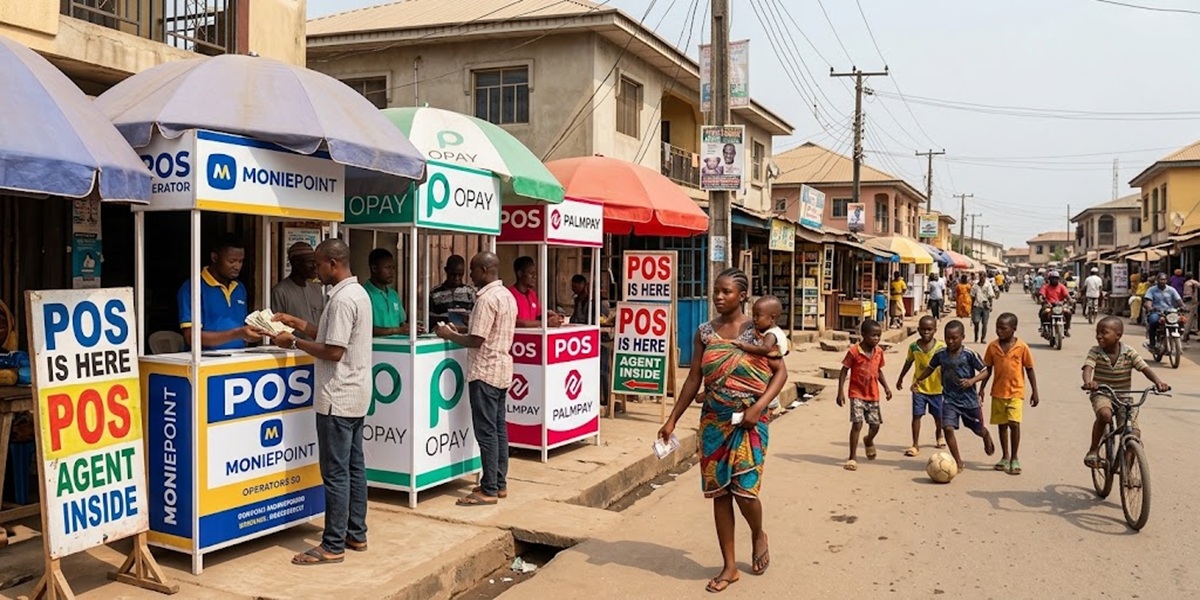
Between October 2025 and August 2026, the Central Bank of Nigeria executed a comprehensive regulatory restructuring of the nation's retail payments architecture. The apex bank introduced strict transaction limits, banned multi-principal terminal operations, and established geographic boundaries to regulate the rapid expansion of mobile money agents and financial technology firms.
Data from the [Nigeria Inter-Bank Settlement System](https://nibss- plc.com.ng/) indicates that the total number of deployed point-of-sale devices nationwide expanded by 127.07 per cent to reach 5.56 million by late 2024. Transaction volumes continued to climb sharply, culminating in ₦18.78 trillion processed through terminals during the first quarter of 2026 alone.
Why did the central bank intervene in agency banking?
The regulatory changes were designed to address severe supervisory challenges stemming from the rapid growth of informal cash rails. According to financial regulators, the proliferation of unmonitored devices created vulnerabilities exploited for ransom payments, fraud, and illicit cash hoarding that depleted physical currency at traditional bank branches. By restricting market dominance and establishing rigid oversight frameworks, Abuja sought to balance financial access with national security and monetary control.
How does the single-principal mandate affect operators?
Under the revised Regulatory Framework for Agent Banking, agents are prohibited from operating devices from multiple financial institutions simultaneously. Merchants must register with the Corporate Affairs Commission and affiliate with a single principal provider. Furthermore, daily customer withdrawals are capped at ₦100,000 per individual and ₦500,000 weekly, while individual agent cash-out volumes are restricted to a maximum of ₦1.2 million per day.
What are the rules regarding terminal geo-fencing?
To prevent the unauthorized relocation of registered hardware, the apex bank mandated that all payment terminals operate within a strict 70-metre radius of their officially registered business location. Originally proposed with a tighter 10-metre constraint, the boundary was expanded following industry feedback to accommodate urban spatial constraints. This policy requires terminals to transmit rich data messages via licensed payment aggregators while ensuring mobile or roaming agents remain tied to fixed coordinates.